The short answer
Venture debt is a loan for startups that are already funded by investors and growing fast. It complements equity but does not replace it. You get money without giving up shares right away, but you pay interest, meet conditions and usually give the lender a small equity option. It makes the most sense for extending the time until the next funding round. As of October 2026.
How venture debt works
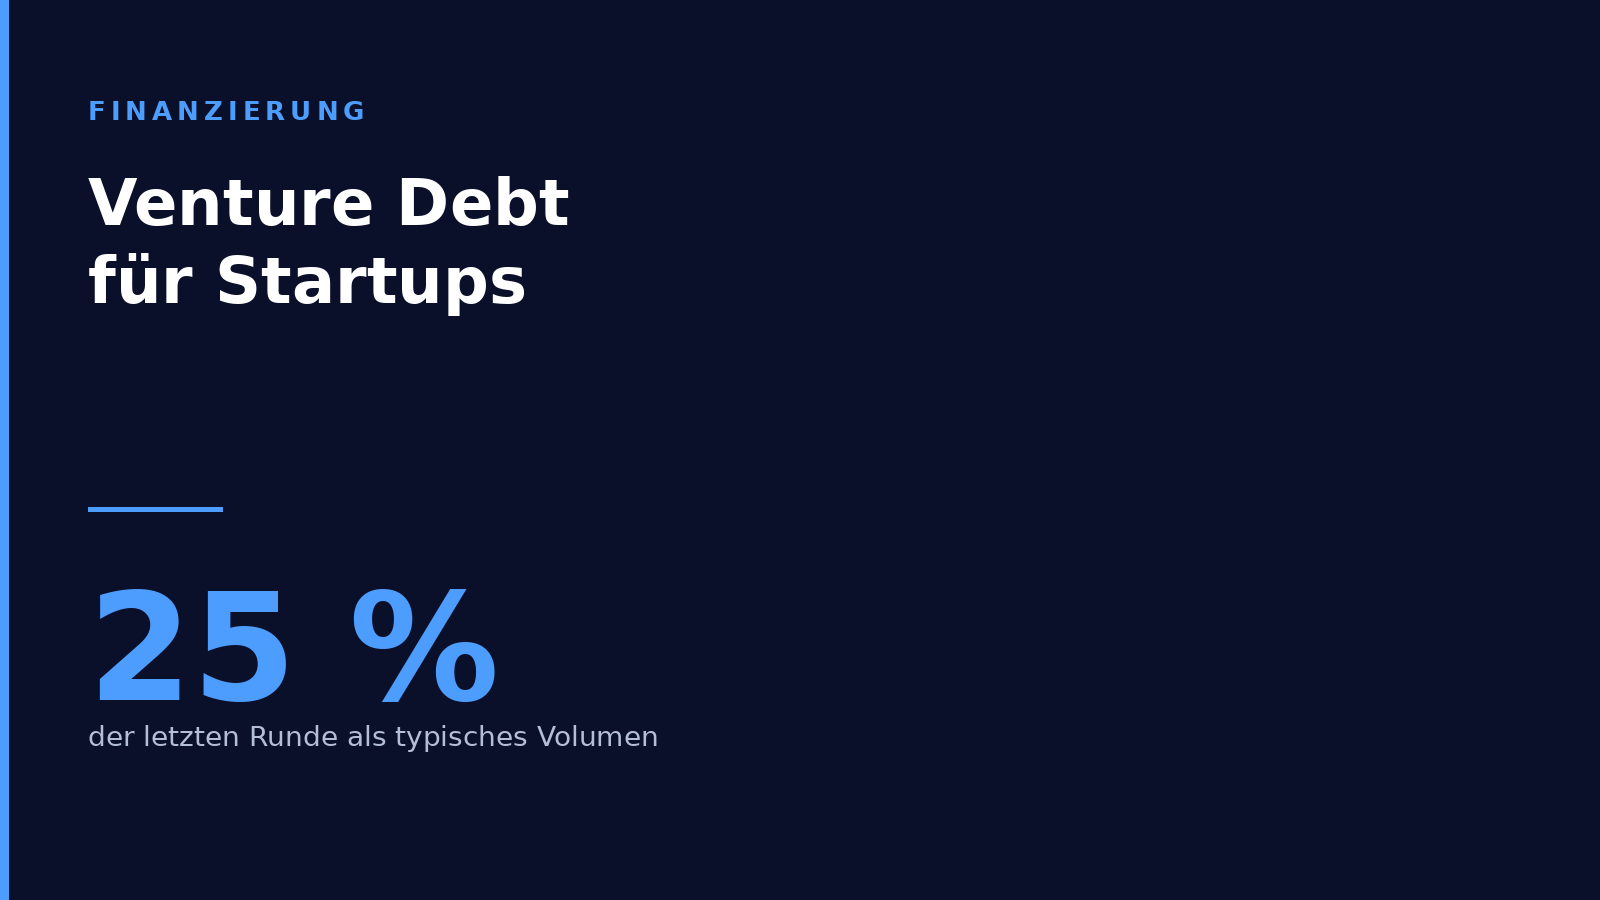
Specialised lenders usually provide venture debt shortly after an equity round, because the investors then act as a safeguard. The term is often a few years, frequently with a period at first in which only interest is paid. The amount is usually based on the last round or on recurring revenue. The exact terms differ widely between providers and market phases.
What venture debt costs
The cost has several parts: interest, an arrangement fee and warrants. Warrants are options to buy shares later at a fixed price. Current market overviews cite a low single-digit percentage for them. Whether that figure refers to the loan amount or to company shares is not consistent. So have the calculation in the offer explained to you in detail, and work out the total cost before you sign.
Covenants: the conditions
Lenders usually require you to meet certain ratios, for example a minimum cash balance or minimum growth. If you breach them, the lender can terminate the loan or renegotiate it. How to build such conditions into your reporting is shown in Covenant reporting for banks and debt funds.
When venture debt makes sense
- Extend runway: You want to gain several months to reach better metrics for the next round.
- Fund a specific goal: For example equipment or a milestone that raises value significantly.
- Limit dilution: You want to give up fewer shares than an additional equity round would require.
When it does not fit
Without investors behind you and without reliable income, venture debt is risky. Interest and repayments keep running even if growth fails to appear. If cash is tight anyway, a loan adds risk. First check whether you can solve the problem more cheaply, for example through less working capital tied up or bridge financing from existing investors, such as a convertible loan.
Preparation: what lenders want to see
Lenders mainly check whether you can show repayment from your plan. That takes a reliable cash plan, current figures and a clean cap table. The 13-week cash flow forecast is a good building block here, because it shows when money comes in and goes out. Also watch for early warning signs of a cash squeeze before you negotiate: anyone negotiating under time pressure gets worse terms. The overview of raising capital is in the article Fundraising for startups.
Frequently asked questions
What is venture debt?
Venture debt is a loan for startups backed by investors. It complements equity and often extends the time until the next funding round.
What are warrants in venture debt?
Warrants are options to buy shares later at a fixed price. They are part of the lender's compensation, alongside interest.
Who is venture debt suited for?
Mainly fast-growing startups that have already closed an equity round and can show predictable revenue or strong investors.
Does venture debt replace a funding round?
No. It extends the time until the next round, but does not replace equity and must be repaid.
Sources
re-cap, venture debt market overview (August 2026); Gründerfreunde, venture debt explained (June 2026). As of October 2026. Terms change, and this article does not replace financial or legal advice.